Excavator Financing Rates, Down Payments and Loan Terms

Excavator financing math: each Kubota rebate breaks even below a 4.4% loan rate, while one posted bank sheet starts equipment loans at 7.25% APR.
Table of Contents
Rates and sources checked on October 28, 2026.
New in-stock Kubota, Cat and Deere compact excavators carry 0% APR for up to 60 months on factory offers that run through at least December 31, 2026, while Minnesota-based United Prairie Bank’s posted equipment loan rates run 7.25% to 10.75% APR for commercial and farm borrowers. At those bank rates, 0% costs less than every Kubota cash rebate, because each rebate only comes out ahead when the balance can be borrowed below about 2.6% to 4.4%.
A cash buyer is the exception, since a rebate with nothing to finance is simply money off the price. Used excavators sit outside all three factory programs, so a used machine is priced on bank terms alone.
Which is cheaper, 0% or the Kubota cash rebate?
Kubota is the only one of the three brands that posts a cash alternative next to its 0% rate, so the trade can be worked model by model. Kubota’s excavator offer gives 0% for up to 60 months on new K, KX and U series machines from dealer stock, or an instant rebate with cash or standard-rate financing, never both.
| Model | Kubota MSRP, USD (offer ends 12/31/26) | Instant rebate, USD | 0% payment, 60 months | Break-even loan rate |
|---|---|---|---|---|
| U10-5 | $31,045 | $2,000 | $517 | 2.65% |
| U17-5 | $37,920 | $2,500 | $632 | 2.72% |
| U27-4 | $45,713 | $3,550 | $762 | 3.23% |
| U35-4 | $56,147 | $5,400 | $936 | 4.05% |
| KX040-5 | $68,768 | $7,000 | $1,146 | 4.31% |
| U55-5 | $82,642 | $8,500 | $1,377 | 4.36% |
| KX057-5 | $88,140 | $8,500 | $1,469 | 4.06% |
| KX080-5 | $138,273 | $12,000 | $2,305 | 3.63% |
MSRPs are Kubota’s “as low as” figures from its offer page. Rebate amounts are from Kubota’s offer terms as posted by ABC Equipment Rental & Sales. Break-even rates are worked out by setting the 0% payment over 60 months equal to the payment on MSRP minus the rebate over the same term, then solving for the interest rate.
Take the KX080-5. With the rebate, $126,273 is left to finance. At 7.50% (United Prairie’s 700+ credit rate for $75,000 to $199,999 over four to five years) the payment comes to $2,530 a month. Across the five years that totals $151,815, $13,542 more than taking 0%. One credit tier down, at 9.50%, the gap widens to $20,845.
Kubota Credit’s standard rate isn’t posted on the offer page, so United Prairie’s sheet stands in as the outside rate here.
The rebate’s share of the price decides the break-even. These rebates run 6% to 10% of MSRP, which is why none of the break-evens reaches 4.5%. A dealer price below MSRP with the same rebate pushes the break-even up slightly, so rerun the comparison with the price on your written quote.
Kubota, Cat and Deere offers on new compact excavators
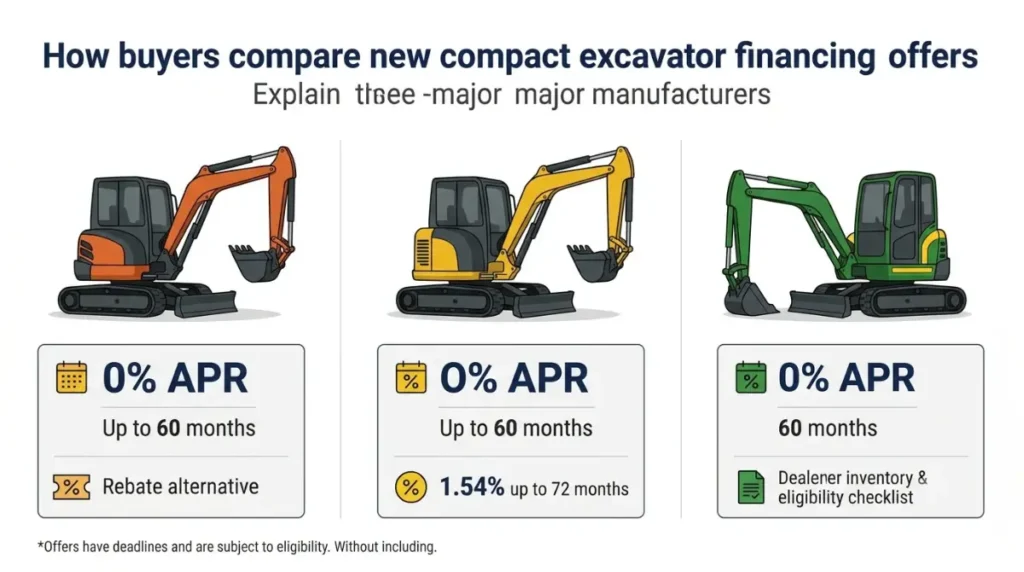
Banner headlines make the three offers look alike. The fine print splits them on down payment and deadline.
| Brand and models | Rate and term, US offers | Down payment wording | Offer ends |
|---|---|---|---|
| Kubota K, KX and U series, dealer stock | 0% up to 60 months, or instant rebate | “$0 Down” headline | 12/31/26 |
| Cat 300.9D to 310 mini excavators | 0% up to 60 months, or 1.54% up to 72 months | Not stated on Cat’s offer page | Purchase and delivery by 12/31/26 |
| Deere compact excavators, dealer inventory | 0% for 60 months | “Average down payment is 10%” | 1/4/27 |
Sources: Kubota excavator offer terms, Cat compact equipment offers, John Deere compact construction equipment offer.
Cat’s 72-month option buys a smaller payment with interest. Take $60,000 financed as an example. At 0% over 60 months the payment is $1,000 a month; at 1.54% over 72 months it is $873 a month with $2,853 in interest. That is $2,853 to lower the payment by $127.
Purchases from October 1, 2026, qualify for the Deere offer, on installment credit from John Deere Financial for commercial use only. Every one of these offers is subject to credit approval by the brand’s finance arm, and Cat’s terms state that not all customers will qualify.
Bank loan rates by credit score and loan size
| Loan amount | 700+ credit, 2 to 5 years | 700+ credit, 6 to 7 years | 660 to 699 credit, 2 to 5 years | 660 to 699 credit, 6 to 7 years |
|---|---|---|---|---|
| $200,000 and up | 7.25% | 7.50% | 9.25% | 9.50% |
| $75,000 to $199,999 | 7.50% | 7.75% | 9.50% | 9.75% |
| $25,000 to $74,999 | 7.75% | 8.00% | 9.75% | 10.00% |
| $5,000 to $24,999 | 8.50% | 8.75% | 10.50% | 10.75% |
APR from United Prairie Bank’s equipment financing sheet, dated 10/20/2026, for commercial and agricultural borrowers only. The sheet covers new and used purchases, up to 100% of the price plus tax, title, license and fees, on terms up to 84 months.
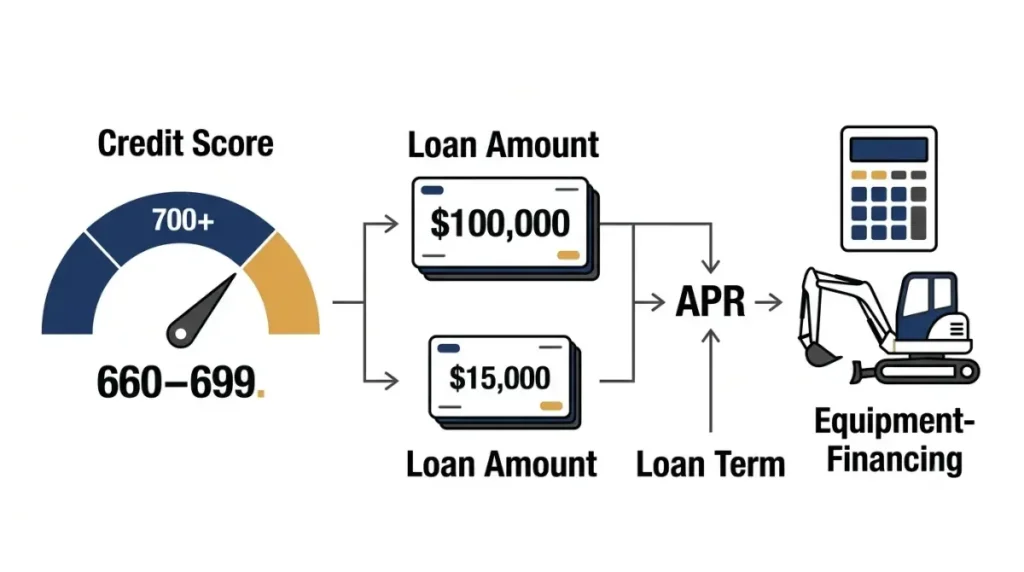
Credit score moves this sheet more than loan size does. Dropping one credit tier adds two points at every loan size, while the smallest loans pay 1.25 points more than the largest. Treat it as one dated reference point from one lender to hold a dealer quote against.
Because the factory 0% programs cover new stock only, a used excavator is financed at rates like these, so check the wear items that set a used excavator’s value before you size the loan.
SBA-backed loans come with a ceiling on the rate. The SBA’s 7(a) loan terms cap a variable-rate loan of $50,001 to $250,000 at the base rate plus 6.0 points. They also hold most equipment loans to 10 years unless the equipment’s useful life runs longer. The lender sets your rate under that cap.
$90,000 financed over 36 to 84 months
Term length moves the total cost of a bank loan more than anything else on the sheet.
| Term | APR, 700+ credit tier for this loan size (sheet above) | Monthly payment | Total interest |
|---|---|---|---|
| 36 months | 7.50% | $2,800 | $10,784 |
| 48 months | 7.50% | $2,176 | $14,453 |
| 60 months | 7.50% | $1,803 | $18,205 |
| 72 months | 7.75% | $1,567 | $22,826 |
| 84 months | 7.75% | $1,392 | $26,892 |
Standard amortization worked from the posted rates, which step up 0.25 points for 6- and 7-year terms.
Going from five years to seven cuts the payment by $411 and adds $8,687 in interest.
That trade suits a machine with steady work booked. A mini bought for weekends needs a payment it can carry in a slow month, which the side-work affordability breakdown for a mini excavator works through.
Down payment moves the total less than term does. Ten percent down on a $100,000 machine matches the five-year row above. Putting 20% down instead drops the payment to $1,603 and interest to $16,182, so the second $10,000 saves $2,023.
What the finance contract says beyond the rate
Kubota’s “$0 Down” headline has a condition in its eligibility footnote: “For eligibility, customer must pay a percentage of sales price, fees, and taxes per the table below. Subject to amount financed.” That chart sits with the dealer, keyed to the amount financed, so a buyer can’t read the required cash from the banner. Deere’s terms say outright that a down payment may be required.
The other terms that change what you sign:
- Stock only: Kubota and Deere tie their 0% offers to dealer inventory, so the unit has to come off the dealer’s lot.
- Delivery deadline: Cat’s cutoff covers delivery as well as purchase, so a machine still in transit at year-end misses it.
- Who is excluded: Kubota’s program is not open to rental, national-account or government buyers.
- Blended rate: Kubota warns that adding equipment outside the program can raise the APR on the whole contract.
- Payment add-ons: taxes, freight, setup, insurance, fees and delivery can raise the monthly payment under Deere’s offer terms.
- One offer only: Cat’s offer cannot be combined with any other.
None of these show up in the headline rate.
Before you sign: ask the dealer for Kubota’s down-payment chart for your amount financed, and confirm in writing that the serial number on the contract is a stock unit eligible for the offer.
Ask for the cash price before you pick a rate
Get two figures on the dealer’s quote: the price after any rebate, and the total of payments at 0%. Then price the first figure borrowed at your own lender’s rate over the same term, and compare the totals. On every Kubota model in the break-even table, the 0% total comes out lower at any rate on United Prairie’s sheet.
If your yearly hours are still a guess, the financing question comes second. Work out whether owning beats renting at your hours first, and match the machine to the work with the excavator size and cost guide.